The Definitive Guide to Average Mortgage Pre-Approval Amount
Current Benchmarks for the Average Mortgage Pre Approval Amount
Mortgage market activity reflects persistent buyer demand alongside evolving lending standards. Origination platform metrics indicate that loan sizes have adjusted across recent quarters as interest rates and property valuations stabilize. The average preapproved loan amount increased from $326,714 in Q1 2025 to $367,305 in Q2 2025, before settling at $328,997 in Q3 2025 as homebuyers paired slightly lower loan sizes with larger down payments.
According to HousingWire data on pre-approval amounts, the average purchase price tracked across active pre-approval letters sat at $423,667 in Q2 2025 and $385,822 in Q3 2025. During this period, average down payments shifted from 13.3% to 14.7%, showing that buyers actively compensate for prevailing borrowing costs by contributing more upfront equity.
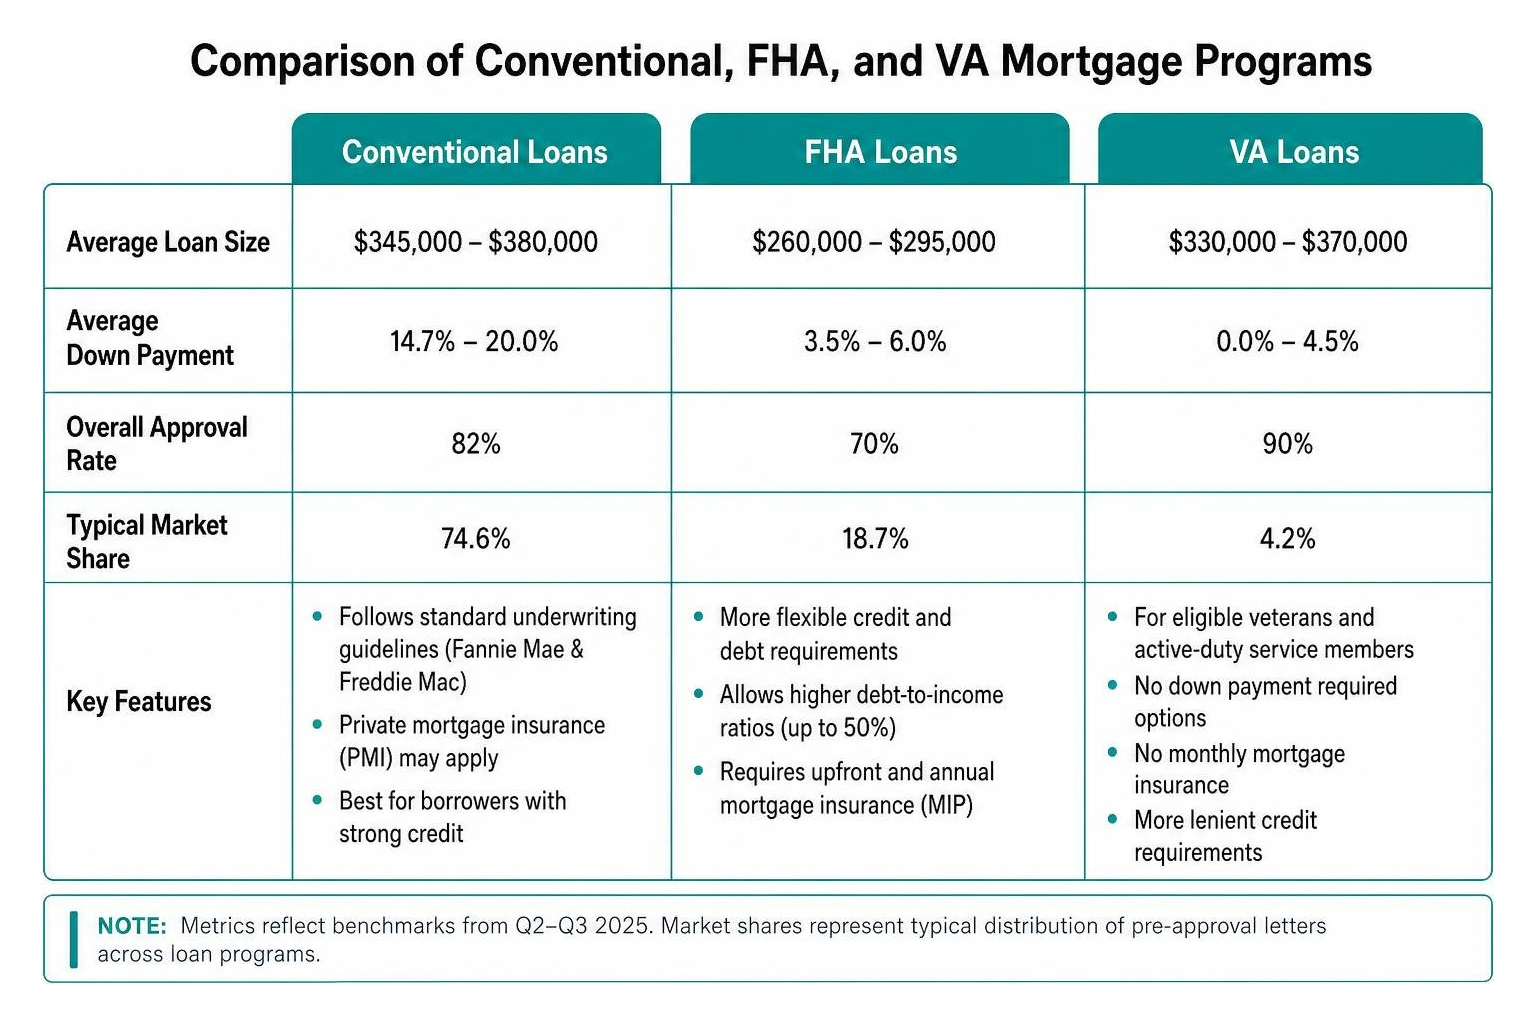
Loan Metric / Program | Average Loan Size | Average Down Payment | Overall Approval Rate | Typical Market Share |
|---|---|---|---|---|
Conventional Loans | $345,000 – $380,000 | 14.7% – 20.0% | 82% | 74.6% |
FHA Loans | $260,000 – $295,000 | 3.5% – 6.0% | 70% | 18.7% |
VA Loans | $330,000 – $370,000 | 0.0% – 4.5% | 90% | 4.2% |
USDA Loans | $210,000 – $250,000 | 0.0% | 85% | 1.0% |
Pre-approval conversion behavior demonstrates that serious buyers take deliberate time navigating property inventories. In Q2 2025, borrowers generated 11.9% more preapproval letters compared to Q1 2025, while the time elapsed between initial pre-approval and formal loan application averaged 86.3 to 89.5 days. Overall, 56% of issued pre-approvals converted directly into active loan submissions, with buyers generating an average of eight customized letters tailored to specific property bids during their search.
Average Mortgage Pre Approval Amount by Loan Type
The structure and underwriting flexibility of individual loan programs significantly impact the final approved borrowing amount.
Conventional Financing: A standard conventional loan represents roughly 74.6% of all pre-approvals. Conventional approval rates averaged 82% in 2023, up from 79% in 2022. These loans follow private mortgage insurance (PMI) guidelines and standard automated underwriting parameters from Fannie Mae and Freddie Mac.
FHA Mortgages: An FHA loan provides an accessible entry point for applicants with lower credit scores or higher debt loads. FHA loans accounted for 18.7% of pre-approvals, holding an average approval rate of 70%. Because FHA financing accommodates back-end debt-to-income ratios up to 50%, some buyers receive higher baseline borrowing figures despite modest incomes, offset by mandatory upfront and annual mortgage insurance premiums (MIP).
VA Financing: Eligible active-duty service members and veterans utilizing a VA home loan benefit from the most favorable underwriting terms available. According to 2026 mortgage approval statistics, VA loan approval rates reached 90% in 2023, driven by lenient credit requirements for veterans, no monthly mortgage insurance, and zero-down-payment options.
First-Time Homebuyers vs. Repeat Buyers
A distinct divide exists between entry-level purchasers and move-up buyers. According to Federal Reserve data, the average pre-approved loan amount for a first time home buyer hovered at $285,000. First-time buyers face an overall mortgage approval rate of 60%, which is approximately 25 percentage points lower than the 85% approval rate recorded for repeat buyers.
Repeat buyers generally benefit from accumulated home equity from prior property sales, enabling higher down payments (often exceeding 20%) that lower loan-to-value (LTV) ratios. This built-in equity cushion reduces lender risk, eliminates private mortgage insurance, and significantly expands maximum borrowing capacities compared to first-time shoppers who rely primarily on personal savings.
How Underwriters Determine Your Pre-Approval Limit
Mortgage underwriting relies on standardized mathematical risk calculations rather than guesswork. Lenders evaluate how much monthly cash flow you have available to cover a housing payment after servicing all other recurring obligations.
Translating Annual Salary with the 2.5x to 3x Rule
When providing a preliminary estimate, most lenders estimate your maximum preapproval at 2.5 to 3 times your annual salary. This rule of thumb provides a quick baseline for establishing a realistic price range before full asset verification.
Gross Annual Income | 2.5x Salary Multiplier | 3.0x Salary Multiplier | Estimated Comfortable Max Purchase Price* |
|---|---|---|---|
$70,000 | $175,000 | $210,000 | $230,000 – $245,000 |
$100,000 | $250,000 | $300,000 | $310,000 – $340,000 |
$150,000 | $375,000 | $450,000 | $475,000 – $510,000 |
$200,000 | $500,000 | $600,000 | $625,000 – $680,000 |
*Estimated purchase price assumes a 10% to 15% down payment added to the loan balance under standard property tax and insurance profiles.
While helpful, this multiplier simplifies complex factors. The final pre-approval amount depends on your total monthly housing payment (PITI: Principal, Interest, Taxes, and Insurance), homeowners association (HOA) fees, and existing monthly debt.
The Critical Role of DTI and Credit Scores
Underwriters evaluate borrowing limits using two primary pillars: Debt-to-Income (DTI) ratios and credit scores.
The standard benchmark across the mortgage industry is the 28/36 rule:
Front-End DTI (28%): Your total monthly housing expense (mortgage principal, interest, property taxes, hazard insurance, and HOA dues) should not exceed 28% of your gross monthly income.
Back-End DTI (36%): Your total monthly debt obligations (housing costs plus auto loans, student loans, minimum credit card payments, and personal loans) should not exceed 36% of your gross monthly income.
Empirical lending data underscores the importance of this ratio: 95% of applicants with a debt-to-income ratio below 36% were approved for mortgages in 2023, whereas approval rates dropped to 60% for applicants carrying DTI ratios between 41% and 50%.
Credit scores dictate the interest rate tier applied to your loan, which directly alters the monthly principal-and-interest payment and shifts your maximum borrowing limit. In 2023, only 20% of applicants with a credit score below 620 were approved for a mortgage, compared to a 70% approval rate for borrowers in the 680 to 720 bracket, and over 90% for borrowers with scores above 740.
For high-balance properties in high-cost metro markets, staying within standard limits requires checking your local conforming loan maximum to determine whether a standard conventional or jumbo loan is required.
Navigating the Approval Stages and Common Pitfalls
Securing a mortgage involves distinct underwriting stages. Understanding where you stand in the pipeline prevents misunderstandings when making purchase offers.
The average mortgage approval process took 45 days in 2023, down from 52 days in 2022, with simple W-2 files closing in roughly 30 days while complex or jumbo files require closer to 60 days.
Pre-Qualification vs. Pre-Approval vs. Conditional Approval
A home loan pre approval differs fundamentally from basic automated estimates:
Pre-Qualification: An informal calculation based on self-reported financial figures and an optional soft credit check. It carries no underwriting verification and offers minimal assurance to home sellers.
Pre-Approval: A rigorous process where an underwriter pulls a tri-merge credit report and verifies official financial documentation, including 30 days of pay stubs, two years of W-2s, and two months of bank statements. According to HMDA pre-approval research, fully verified pre-approvals substantially increase origination success rates and narrow closing gaps for prospective buyers.
Conditional Approval: Issued once an underwriter reviews the complete loan file and issues a commitment letter subject to final property verification, such as a satisfactory appraisal, clean title search, and proof of homeowners insurance.
Why Pre-Approved Loans Get Denied Before Closing
A pre-approval letter is not an unconditional guarantee. In 2023, the overall mortgage approval rate was 75%, and loans can fall out of underwriting if a borrower's financial status changes prior to closing.
The most common reasons for mortgage rejection during final review include:
Insufficient or Altered Income Documentation (30% of denials): Changing employers, moving to commission-based structures, or taking unpaid leaves.
Credit Score and New Inquiries (25% of denials): Financing a new vehicle, opening retail credit cards, or missing payment due dates during escrow.
Property Appraisal Shortfalls (15% of denials): When a home appraises below the agreed purchase price and the buyer cannot cover the valuation gap.
Undisclosed Debts or Asset Movement: Unexplained large cash deposits that fail anti-money-laundering sourcing requirements.
Actionable Steps to Boost Your Borrowing Power
If your initial borrowing assessment falls short of home prices in your target neighborhood, structured financial adjustments can expand your purchasing capacity.
Strategies to Increase Your Average Mortgage Pre Approval Amount
Pay Down Revolving Balances: Lenders qualify you based on required minimum monthly debt payments rather than total outstanding debt balances. Eliminating a $400 monthly car payment or paying off high-interest credit cards can increase your pre-approved loan capacity by $40,000 to $60,000 under a 43% DTI cap.
Correct Errors on Credit Reports: Dispute inaccurate late payments, remove incorrect collections, and keep credit card balances below 10% to 30% of individual credit limits. Moving your score from 670 to 740 lowers your interest rate and monthly PMI premiums, directly increasing your maximum loan amount.
Document Alternative Stable Income: Ensure all eligible compensation streams—such as verified bonuses, overtime, part-time jobs with a two-year history, or child support—are fully documented with your loan officer.
Shop Within Consolidated Inquiry Windows: FICO and VantageScore algorithms group multiple mortgage credit inquiries made within a 14-day window as a single hard pull, allowing you to compare lender terms without damaging your credit profile.
Add a Qualified Co-Borrower: Applying jointly with a spouse or co-borrower combines qualifying incomes. Across the industry, joint applications achieved a 91% approval rate in 2023, compared to 76% for single applicants.
Frequently Asked Questions About Mortgage Pre-Approval
How long does a mortgage pre-approval letter remain valid?
A mortgage pre-approval letter is typically valid for 60 to 90 days. This expiration timeline exists because credit reports expire after 90 to 120 days, and market interest rates fluctuate constantly. If your search extends past 90 days, your lender will simply request your most recent pay stub and bank statement to issue an updated letter.
How many pre-approval letters should a homebuyer generate while shopping?
Borrowers generate an average of eight pre-approval letters during their home search. Rather than submitting a pre-approval showing your maximum qualification limit, your loan officer can issue customized letters that match the exact offer price on each specific property, preserving your negotiating leverage with sellers.
Does shopping around for multiple pre-approvals hurt your credit score?
No, provided your applications occur within a focused timeframe. Credit scoring bureaus recognize mortgage shopping and treat all mortgage credit inquiries submitted within a 14-day window as a single hard credit pull. This typically results in a temporary 5-point score change that recovers within a few months of standard payment history.
Conclusion
Understanding how underwriters calculate your purchasing power ensures you target homes that align with your long-term financial health. While current national benchmarks place the average mortgage pre approval amount between $328,997 and $367,305, your personal borrowing limit is shaped by your gross income, recurring debt commitments, down payment assets, and credit profile.
Taking deliberate steps to lower revolving monthly balances, maintain a clean credit profile, and select the appropriate loan program gives you a distinct advantage in today's housing market. When you are ready to explore your financing options, calculate your accurate purchasing power, and establish a clear budget, visit buy a home to start your pre-approval process.